EnEn
24/7
(813) 368-5382
Having a property insurance claim denied can leave homeowners and business owners with important questions about what happened and what options may be available.
At All Claims Solutions, our licensed Public Adjusters help Tampa property owners review their claim documentation, evaluate the reported damage, understand relevant policy provisions, and navigate the insurance claims process after a denial.
We work for YOU, not insurance companies.
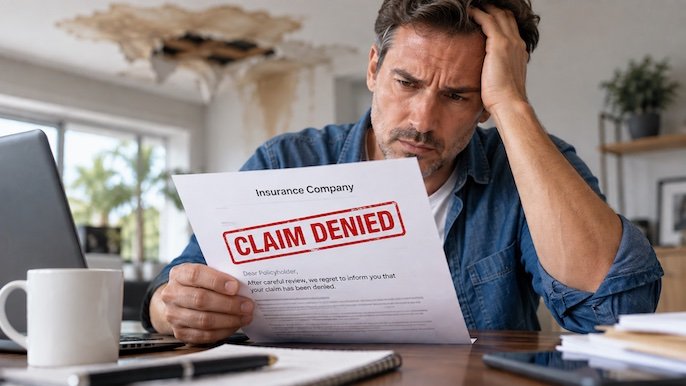
An insurance claim denial generally means that the insurer has determined that the reported loss, or some part of it, is not covered or does not meet the requirements of the applicable policy.
The reason for a denial can vary significantly.
For example, an insurer may raise questions involving:
A denial should therefore be reviewed in the context of the specific policy, facts, inspection findings, and supporting documentation.
Florida law requires property insurers to have claims-handling procedures covering investigation, evaluation, estimates, claim decisions, and communication with policyholders
Every claim is different, but a denial may involve one or more of the following issues.
The insurer may determine that the cause of loss falls under an exclusion in the policy.
The insurer and policyholder may have different conclusions about what caused the damage.
For example:
Roof damage → water intrusion → interior damage
The cause and sequence of events can become important when evaluating coverage.
An insurer may request photographs, estimates, receipts, reports, or other information needed to evaluate the loss.
The insurer may assert that a particular policy condition was not satisfied.
The insurer may determine that some damage resulted from wear, deterioration, maintenance issues, or another condition excluded by the policy.
Additional damage may be discovered after the original claim was submitted.
Water damage following a storm or hurricane can raise different coverage questions depending on the source of the water and the applicable policy.
Important: These are examples, not conclusions about any particular claim. The reason stated in the insurer’s denial letter and the applicable policy language should be reviewed carefully.
Look for:
What does the insurance company say caused the loss?
What section, exclusion, limitation, or condition does the insurer cite?
What damage did the insurer inspect or acknowledge?
What photographs, reports, estimates, or inspections were used?
Does the insurer identify documentation that could affect its evaluation?
Understanding these elements can help determine what additional review or documentation may be appropriate.
At All Claims Solutions, we help Tampa property owners understand and navigate the insurance claims process after a claim has been denied.
Our approach includes:
We review available claim information, including the denial documentation and information about the reported loss.
We inspect the property and document visible and potentially related damage.
We examine available policy information, including relevant coverages, exclusions, limits, and endorsements.
We organize photographs, estimates, reports, receipts, inventories, and other supporting documentation relevant to the claim.
Where appropriate, we help prepare and present the documented loss based on the applicable policy and supporting evidence.
As the policyholder’s Public Adjuster, we assist with communications and negotiations concerning the documented claim.
A denied residential claim can affect homeowners dealing with significant property damage.
Potentially affected areas may include:
A denial may involve questions about the cause of damage, policy coverage, exclusions, documentation, or the scope of the loss.
For a business, a denied property insurance claim can involve more than the cost of repairing a building.
Potential claim components may include:
Commercial policies can contain different coverages, exclusions, endorsements, limits, and conditions.
All Claims Solutions helps Tampa homeowners navigate the claim review process and organize the information needed to understand their situation.
At All Claims Solutions, our licensed Public Adjusters represent policyholders—not insurance companies.
We help homeowners and businesses navigate complex property insurance claims involving:
Our existing Tampa positioning emphasizes policyholder representation, policy evaluation, property inspection and handling the claims process.
We can evaluate the available policy information and property damage to help determine what documentation and claim assistance may be appropriate.
All Claims Solutions assists property owners throughout Tampa and surrounding communities.
We serve areas including:
Claims involving wind, roof damage, water intrusion, and other hurricane-related property damage.
Claims involving wind, hail, rain-related damage, and other storm losses.
Claims involving plumbing failures, leaks, water intrusion, and other covered water-related losses.
Claims involving fire, smoke, soot, firefighting-related water damage, and related property losses.
Claims involving storm-related or other covered roof damage.
→ Roof Damage Claims
Claims involving mold-related property damage where applicable coverage exists.
Claims involving damage to structural components of residential or commercial properties.
All Claims Solutions helps Tampa property owners review, document, and navigate denied property insurance claims.
All Claims Solutions – Tampa, FL
24/7: (813) 368-5382
Email: info@all-claims.com

Our public adjusters work hard 24/7. We know that claim issues can happen any day or time and so we are «standing by.» Call us today to schedule a free consultation.

We will only get paid if you get paid. Our licensed professional adjusters can assist you in negotiating and analyzing your insurance claim to get you the best settlement possible and represent YOU

Our licensed public adjusters can provide you with a FREE insurance policy evaluation, on site inspection and estimate for your property loss. We have the skills to get you indemnified and we will be on your side in case of future loss or damages.
Please fill out the form and press the submit button.
We will get back to you with 1-2 business days.